Audit, Tax & Advisory

TRI-S-AUDIT

Audit of financial statements under ISA, IFRS transformation, tax and legal opinions. Our own methodology, transparent quality control and a technology contour operated under partner supervision.

№ 6in the register of audit organisations of the Ministry of Finance since 2021
ISA · ISQM 1audit and quality management under the international standards
IFRStransformation, first-time adoption, consolidation
RU · EN · UZreports and opinions in three languages
Photo: Rohit Tandon, Unsplash

Who we are

Independent audit under international standards

We are entered in the register of audit organisations of the Ministry of Finance of the Republic of Uzbekistan under No. 6 and work under the International Standards on Auditing, the International Standards on Quality Management and the IESBA Code of Ethics, as recognised in Uzbekistan.

The firm is led by two partners: the managing partner is responsible for engagements and clients, the partner responsible for quality for the quality system, the methodology and the review of every report before issue. We do not audit financial statements that we prepared or transformed ourselves for the same period.

Reports, opinions and correspondence are in Russian, English and Uzbek.

More about the firm

Services

What we do

Nine kinds of engagement, from an ISA audit to forensic work. Each passes the same gates: acceptance, risk-based planning, data procedures, quality review, issue.

ISA · ISQM 1 · ZRU-677

Audit of financial statements

An independent opinion on the fair presentation of financial statements under NAS or IFRS, performed under the International Standards on Auditing. For owners, banks, investors and the regulator.

ISRE 2400 · ISRE 2410

Review of financial statements

Limited assurance on financial statements based on inquiries and analytical procedures under ISRE 2400, when a full audit is not required but an owner, bank or partner needs assurance.

ISRS 4400

Agreed-upon procedures

Testing of specific facts against a list agreed with the client, for a bank, investor, donor or parent company. A report of factual findings without expressing assurance (ISRS 4400).

IFRS 1 · IFRS 10 · ISRS 4410

IFRS reporting and transformation

Transformation of financial statements from NAS to IFRS, first-time adoption under IFRS 1 with three reconciliations, group consolidation and a full set of financial statements with notes. For investors, banks and parent companies.

Tax Code of Uzbekistan · IESBA 604, 608

Tax and legal advice

Written opinions on tax and legal questions with the answer in the first paragraph, numbered arguments and references to provisions on lex.uz in the edition in force. Support in tax inspections and disputes.

ISA 315 · ZRU-764 · COBIT

Data security and integrity report

Review of the general IT controls of the accounting system and the integrity of accounting data, as part of an audit or as a separate engagement. Assessment through nine integrity tests, graded A to D, and a report for management.

Approach

How we work

Five rules that are the same for every engagement and are set out in the public description of the quality system.

  1. Acceptance and independence

    We check conflicts of interest and independence before the engagement letter is signed, not after. The firm does not audit financial statements that it prepared itself for the same period.

  2. Risk and materiality

    Planning is built on the client's risks; materiality levels are documented, explained and agreed with management.

  3. Data, not a sample

    Where possible, we test the whole population of entries: journal entries, Benford distributions, analytics over the full dataset.

  4. Quality control

    The partner responsible for quality reviews every report before it is issued. The system is built on ISQM 1 and ISQM 2 and described publicly.

  5. AI under supervision

    Models prepare drafts and recalculate figures; a human signs; client data is not used to train models.

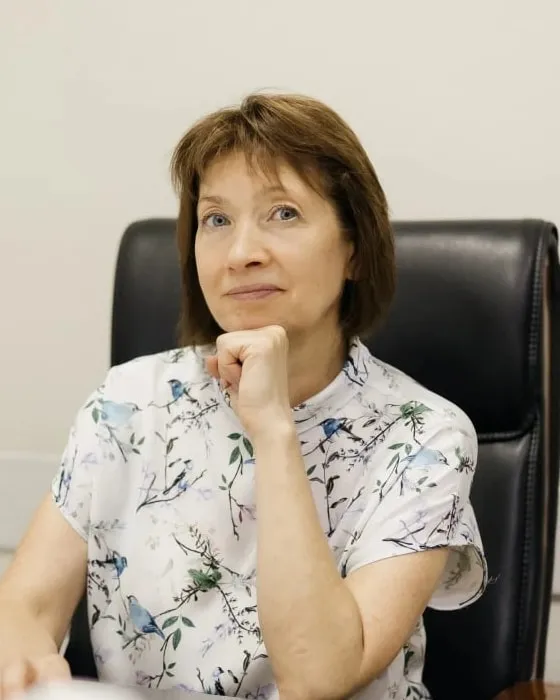
Svetlana Golosova

Leadership

Svetlana Golosova

Managing Partner, Director

The managing partner is responsible for client relationships, engagement acceptance, performance of engagements and issue of reports, and for the firm as a whole before the authorised body.

Leads engagements in audit of financial statements, review engagements and agreed-upon procedures; signs audit reports and correspondence with regulators.

A detailed biography will be added.

Whole team

Articles

Publications by the partners

All posts

Shall we discuss your engagement?

Tell us which financial statements, for which period and for whom the report is needed. We reply within one working day and propose the form of the engagement.